Chenoweth-Brewer v. United States: What the IRS Notice Ruling Says About Proof of Mailing
 Updated October 2026
A recent federal court ruling offers an important reminder for tax professionals, legal teams, compliance departments, and businesses that rely on mailed notices: proof that a notice was properly mailed can be legally significant even when the recipient says the notice was never received.
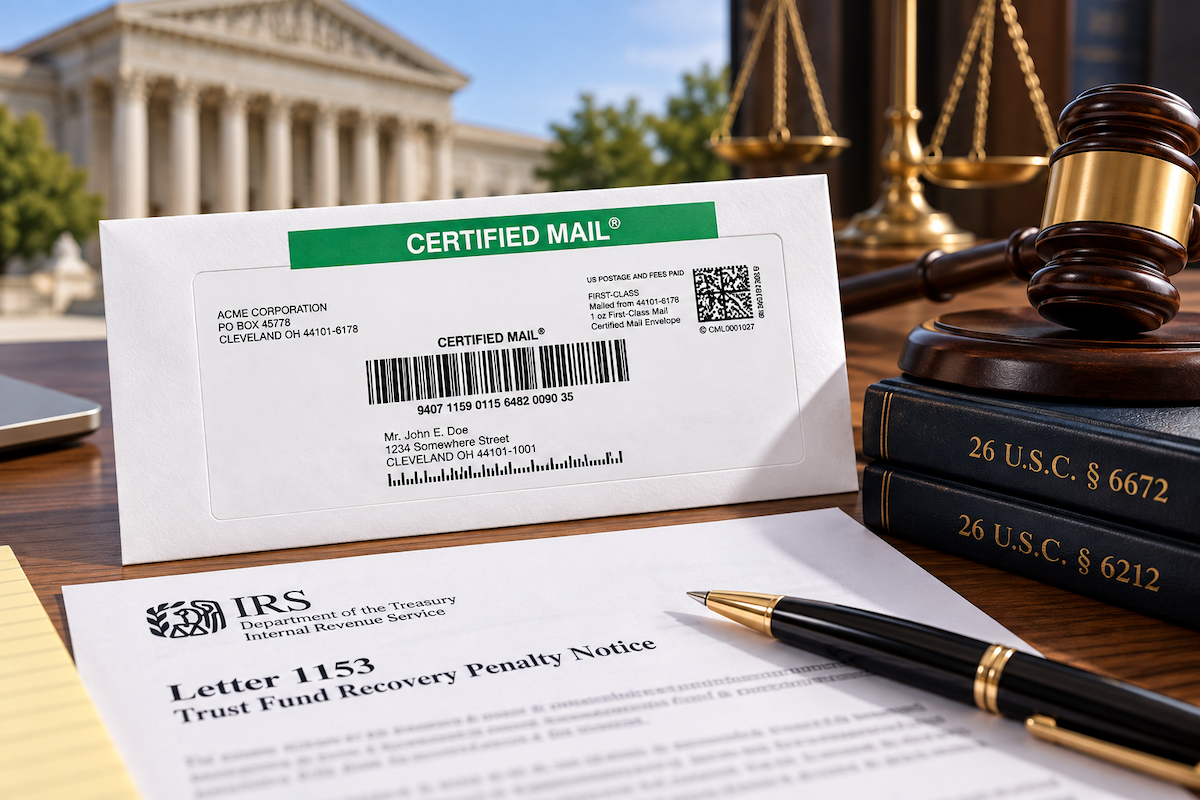
In Chenoweth-Brewer v. United States of America, a federal district court examined whether the Internal Revenue Service satisfied a statutory notice requirement when it sent an IRS Letter 1153 by Certified Mail to a taxpayer's last known address.
The taxpayer said she did not receive the notice. However, the court concluded that the statutes at issue required the IRS to send the notice by Certified or Registered Mail to the appropriate address. Under the facts and law before the court, the government was not also required to prove that the taxpayer actually received the letter.
The September 29, 2026 ruling does not mean that Certified Mail automatically satisfies every legal notice requirement. It does, however, illustrate an important compliance principle: organizations should understand exactly what their governing law requires and maintain records capable of showing when, where, and how a required notice was mailed.
How Certified Mail Became Important in Chenoweth-Brewer
The dispute involved a proposed Trust Fund Recovery Penalty, commonly called a TFRP. Before making certain assessments under 26 U.S.C. § 6672, the IRS must provide the affected taxpayer with notice.
According to the court's order, IRS personnel prepared Letter 1153 on May 16, 2016 and sent it by Certified Mail to the taxpayer's residence. The parties did not dispute that the address used was her residence at the relevant time.
The evidentiary record included several pieces of documentation related to the mailing, including:
- A copy of IRS Letter 1153;
- IRS records relating to the Trust Fund Recovery Penalty process;
- An affidavit from an IRS attorney;
- An Automated Trust Fund Recovery history excerpt;
- Deposition materials; and
- Evidence concerning the address where the notice was mailed.
The taxpayer argued that she had not received the notice. She also challenged aspects of the letter's dating and signature based on procedures contained in the Internal Revenue Manual.
The court ultimately granted the United States partial summary judgment on the notice issue. It concluded that the relevant statutory provisions required the notice to be sent by Certified or Registered Mail to the taxpayer's last known address and did not impose an additional requirement that the government prove actual receipt under the circumstances presented.
What the Court Actually Decided
The distinction between sending a required notice and proving that someone actually received it is central to understanding the decision.
The court considered 26 U.S.C. § 6672(b)(1), which addresses preliminary notice before certain Trust Fund Recovery Penalty assessments, together with the mailing and address provisions contained in 26 U.S.C. § 6212.
Based on the statutory language and the evidentiary record, the court found no genuine dispute that the IRS had sent the Letter 1153 by Certified Mail to the taxpayer's appropriate address.
The court therefore concluded that the statutory notice requirement at issue had been satisfied.
Importantly, this was a ruling on the notice issue. It was not a final determination that the taxpayer was responsible for the underlying Trust Fund Recovery Penalty.
Other questions remained disputed, including whether the taxpayer qualified as a “responsible person” and whether she acted willfully. The court found factual disputes concerning those issues.
Proof of Mailing Is Not the Same as Proof of Delivery
The ruling also provides a useful opportunity to explain a distinction that is often misunderstood in compliance mailing: proof of mailing and proof of delivery are not the same thing.
Proof of Mailing
Proof of mailing documents the mailing event itself. Depending on the service and records involved, it may establish information such as:
- The date an item entered the mailstream;
- The USPS service selected;
- The tracking or article number assigned to the mailing;
- The destination address associated with the mailing; and
- Evidence that USPS accepted the mailpiece.
For Certified Mail, the mailing record can become particularly important when a law, regulation, contract, court rule, or internal compliance policy requires evidence that a notice was sent.
Proof of Delivery
Proof of delivery documents what happened later in the mailing process.
USPS tracking may show delivery, an attempted delivery, availability for pickup, forwarding, return to sender, or other tracking events.
A Return Receipt can provide additional delivery information when that service is requested. Depending on the mailing, this may take the form of a traditional return receipt or an Electronic Return Receipt.
These records serve different purposes.
A mailing record answers a question such as:
“Can we document that this notice was mailed as required?”
A delivery record may help answer:
“What happened to the mailpiece after USPS accepted it?”
Which type of evidence is legally required depends on the specific law or rule governing the notice.
The Taxpayer Said She Never Received the Notice
One of the most important parts of the case is that the taxpayer maintained that she had not received Letter 1153.
The court did not make a finding that she actually received it.
Instead, the court focused on what the applicable statutes required the IRS to do.
Under the provisions applied by the court, evidence that the IRS sent the notice by Certified Mail to the taxpayer's last known address satisfied the statutory mailing requirement addressed in the case.
That distinction is important.
The ruling should not be interpreted to mean that actual receipt never matters. Different statutes and notice procedures may impose very different requirements.
Some rules may require mailing. Others may require delivery, service, a signature, a specific address, personal delivery, posting, publication, multiple mailing methods, or another form of notice altogether.
Compliance teams therefore should not assume that one mailing method works for every notice.
Why the “Last Known Address” Matters
The address used for a compliance mailing can be just as important as the mailing method.
In Chenoweth-Brewer, the address itself was not disputed as the taxpayer's residence at the relevant time. That allowed the court to focus heavily on whether the statutory mailing requirement had been satisfied.
In other disputes, however, the address can become a major issue.
A compliance mailing program should therefore have a documented process for determining which address must be used.
Depending on the governing requirement, that may mean:
- A taxpayer's last known address;
- An address contained in a government record;
- A property address;
- A registered agent's address;
- A contractual notice address;
- A business address; or
- Another address specifically identified by statute or regulation.
Before sending a legally significant notice, organizations should confirm both the required method of mailing and the required destination address.
What About the Internal Revenue Manual?
The taxpayer also argued that the IRS had not followed certain procedures in the Internal Revenue Manual concerning the dating and signing of the notice.
The court rejected the argument that these alleged departures, standing alone, invalidated the notice.
In reaching that conclusion, the court explained that the relevant Internal Revenue Manual procedures did not themselves have the force and effect of law.
That does not mean Internal Revenue Manual procedures are irrelevant in every circumstance. Rather, the court distinguished internal administrative procedures from the statutory requirements controlling the notice question before it.
For compliance professionals, that distinction is another useful reminder: internal procedures, operational best practices, statutory requirements, regulations, and court rules are not always interchangeable.
A Practical Documentation Lesson for Compliance Mailers
Although the case involved an IRS notice, the broader documentation lesson applies to many organizations that send legally significant mail.
A defensible mailing record should make it possible to connect the actual document being sent with the mailing event.
Depending on the law, organizational policy, and mailing workflow, a complete record may include:
- A copy of the final notice.
Retain the actual version of the letter or document that was mailed. - The recipient and mailing address.
Preserve the address used and, when appropriate, the source used to determine that address. - The mailing date.
Document when the item entered the mailstream. - The USPS service selected.
Record whether the item was sent using Certified Mail, First-Class Mail, Priority Mail, or another required service. - The tracking or Certified Mail article number.
Connect the USPS tracking number directly to the underlying notice or matter. - The USPS acceptance record.
When proof of mailing date matters, retaining the USPS acceptance event can help document when USPS took possession of the mailpiece. - Tracking and delivery events.
Preserve available information showing delivery, attempted delivery, forwarding, return, or other USPS activity. - Return Receipt documentation, when applicable.
If a traditional or Electronic Return Receipt is required or requested, retain that record with the mailing documentation. - A complete evidence packet.
Keep the notice and associated mailing records together according to the organization's document-retention requirements.
These are practical recordkeeping considerations. They are not requirements imposed by the Chenoweth-Brewer court.
The precise evidence needed for any compliance mailing should be determined by the law or rule governing that particular notice.
Why USPS Acceptance Records Matter
For organizations sending time-sensitive or legally significant mail, the first USPS acceptance event can be an especially important part of the mailing record.
Printing a Certified Mail label creates a label and tracking number, but it does not by itself establish that USPS actually received the mailpiece.
A USPS acceptance scan documents a separate event: the Postal Service has taken possession of the item.
This distinction becomes important when an organization needs to demonstrate that a notice entered the mailstream by a particular date.
For higher-volume mailings, USPS SCAN Forms can also help organizations present multiple prepared mailpieces for acceptance while creating a consolidated acceptance workflow.
Organizations should still confirm what type of proof the applicable statute, regulation, contract, or court rule requires. An acceptance scan is an important operational record, but no single record should be assumed to satisfy every legal requirement.
Electronic Return Receipt and Additional Delivery Evidence
When delivery documentation is valuable or required, an Electronic Return Receipt (ERR) can provide additional evidence beyond the initial Certified Mail mailing record.
ERR provides an electronic delivery record associated with the Certified Mail piece. This can help organizations maintain mailing and delivery evidence in digital form rather than relying only on paper records.
For compliance teams managing substantial mailing volumes, keeping the notice, tracking information, acceptance event, delivery information, and return receipt documentation together can create a clearer record if the mailing is questioned months or years later.
Again, whether a Return Receipt is legally necessary depends on the requirement governing the specific notice.
What Chenoweth-Brewer Does Establish
The court's ruling supports several narrow conclusions.
- The dispute involved an IRS Letter 1153 concerning a proposed Trust Fund Recovery Penalty.
- The court found undisputed evidence that the IRS sent the notice by Certified Mail.
- The mailing went to the taxpayer's last known address under the statutes applied by the court.
- The court concluded that the applicable notice requirement had been satisfied.
- The court did not require additional proof that the taxpayer actually received the letter under the statutory provisions it applied.
- Alleged deviations from certain Internal Revenue Manual procedures did not, standing alone, invalidate the notice in this case.
What the Ruling Does Not Establish
The limits of the decision are equally important.
The ruling does not establish that:
- Certified Mail satisfies every legal notice requirement;
- Proof of mailing always proves actual receipt;
- Actual receipt is irrelevant under every law;
- Every address used for Certified Mail will satisfy a notice requirement;
- Every Certified Mail tracking record creates legally sufficient evidence;
- Return Receipt is unnecessary for other types of notices;
- Internal Revenue Manual procedures can never matter in another dispute; or
- The taxpayer was ultimately liable for the Trust Fund Recovery Penalty.
The decision was a federal district court order resolving particular issues based on a specific statutory framework and evidentiary record.
What Businesses and Legal Teams Can Learn From the Ruling
The practical lesson from Chenoweth-Brewer is not simply “use Certified Mail.”
The stronger lesson is:
Know what the governing rule requires, use the correct mailing method and address, and retain evidence showing that you followed the required process.
For compliance mail, the process should begin before the envelope reaches USPS.
Organizations should determine:
- What document must be sent;
- Who must receive it;
- Which address must be used;
- What mailing method is required;
- Whether Return Receipt or another delivery service is required;
- What deadline applies;
- What evidence must be retained; and
- How long those records should be preserved.
That process creates a much stronger compliance record than simply retaining a tracking number after the fact.
How Certified Mail Labels Supports Documented Mailing Workflows
Certified Mail Labels provides an online workflow for organizations that need to prepare and track USPS Certified Mail without completing traditional Certified Mail forms by hand.
Users can create Certified Mail labels online, obtain USPS tracking numbers, monitor mailing and delivery activity, and maintain digital mailing records from a centralized account.
For organizations processing larger volumes of compliance mail, batch workflows and USPS SCAN Forms can help organize mailpieces for presentation to USPS and support documentation of the acceptance process.
Electronic Return Receipt options can also provide additional delivery documentation when needed.
Certified Mail Labels maintains mailing records within the user's account, helping organizations retain documentation that may be needed long after the original notice was sent.
These tools support the mailing workflow, but organizations remain responsible for determining which mailing method, address, documentation, and retention requirements apply to their particular legal or regulatory obligation.
Frequently Asked Questions
Did the court find that the taxpayer actually received IRS Letter 1153?
No. The taxpayer maintained that she did not receive the notice. The court resolved the statutory notice issue based on evidence that the IRS sent the letter by Certified Mail to her last known address. Under the statutory provisions applied in the case, the court did not require additional proof of actual receipt.
What mailing rule did the court apply?
The court considered 26 U.S.C. § 6672(b)(1) together with the relevant address-and-mailing provisions of 26 U.S.C. § 6212. The court concluded that the required notice had been sent by Certified Mail to the taxpayer's last known address.
Did the court decide that the taxpayer owed the Trust Fund Recovery Penalty?
No. The ruling resolved the notice issue through partial summary judgment. Other issues remained disputed, including whether the taxpayer was a responsible person and whether she acted willfully.
Is proof of mailing the same as proof of delivery?
No. Proof of mailing documents the mailing event. Delivery records concern what happened after USPS accepted the item, including delivery or attempted delivery. A Return Receipt can provide additional delivery documentation when requested.
Does Certified Mail always provide legally sufficient notice?
No. Mailing requirements vary significantly. A statute, regulation, court rule, contract, or other controlling authority may specify the mailing method, address, deadline, delivery requirement, signature requirement, or type of evidence that must be retained.
Why is the USPS acceptance scan important?
Creating a Certified Mail label establishes a tracking number, but the USPS acceptance event provides evidence that USPS actually took possession of the mailpiece. When mailing dates matter, retaining that acceptance information can become an important part of the organization's records.
The Bottom Line
Chenoweth-Brewer v. United States provides a timely example of why organizations should pay close attention to both the language of a notice statute and the records generated by their mailing process.
In this case, the court concluded that documented Certified Mailing to the taxpayer's last known address satisfied the specific statutory notice requirement before it. The taxpayer's assertion that she never received the notice did not create an additional receipt requirement under the provisions the court applied.
That does not create a universal rule for Certified Mail.
Instead, the decision reinforces a broader compliance principle: follow the exact notice requirement and preserve a record capable of showing what was sent, where it was sent, when it was mailed, and what happened afterward.
For businesses, government agencies, legal teams, tax professionals, property managers, healthcare organizations, financial institutions, and other organizations that send compliance-related notices, building that documentation into the mailing workflow can make the record much easier to retrieve if the notice is later questioned.
Sources
- Chenoweth-Brewer v. United States of America, No. CIV-25-35-D (W.D. Okla. Sept. 29, 2026), Order on cross-motions for summary judgment.
- 26 U.S.C. § 6672(b)(1), preliminary notice requirements relating to the Trust Fund Recovery Penalty.
- 26 U.S.C. § 6212, statutory provisions addressing certain IRS notices and last-known-address requirements.
- United States Postal Service, Certified Mail service information.
Legal Information Disclaimer: This article summarizes one federal district court order for general educational and informational purposes. It is not legal advice. Notice requirements vary by statute, jurisdiction, facts, contract, regulation, and court rule. Organizations should consult qualified legal counsel regarding requirements applicable to a specific notice or matter.