Default Notices, Foreclosure Mailings, and Audit-Ready Files
Mortgage Servicing Is Measured On The Notice Calendar
Mortgage servicing is measured on the notice calendar. Early-intervention letters by day 45. Live contact by day 36. Loss-mitigation acknowledgments within 5 days. The 120-day pre-foreclosure window. Flood-notice deadlines tied to loan transactions.
If your institution cannot show that the right letter went out at the right time, you may face RESPA violations, restitution, foreclosure rescissions, do-overs, borrower disputes and repurchase exposure. A borrower may say, “I never received the loss-mitigation letter.” Your audit file needs more than a template and an internal note. You need objective mailing evidence.
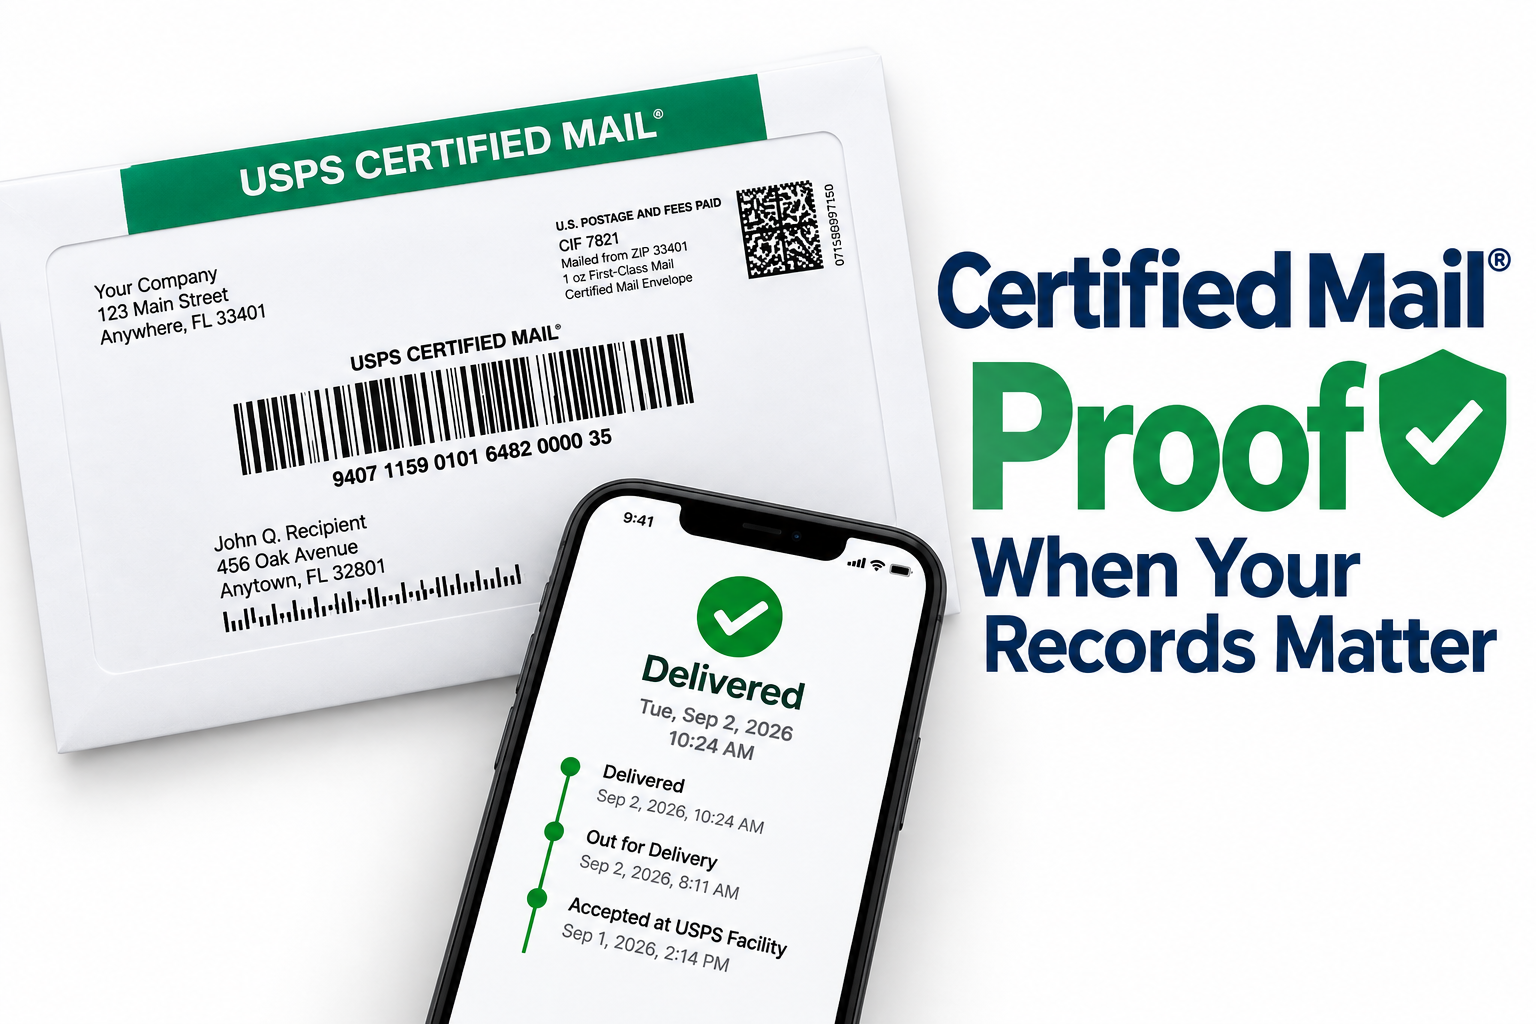
Banks and mortgage servicers use online USPS Certified Mail to create proof of mailing and delivery for early-intervention and loss-mitigation letters, default and acceleration notices, foreclosure-adjacent correspondence, flood-notice letters and payoff or escrow correspondence. You print live-postage Certified Mail labels on any office printer or upload your PDF letter and address list for same-business-day Print & Mail, and you get a notarized affidavit of mailing, USPS acceptance scans, certified mail tracking events and available Electronic Return Receipt signature records stored searchable for 10 years.
Certified Mail Labels helps you execute a dependable legal compliance mailing process without adding monthly software fees, contracts or equipment leases.
What Federal Mortgage-Servicing Rules Require You To Document
Regulation X sets important timing requirements for mortgage servicers:
- By day 36 of delinquency: Under 12 CFR 1024.39, a servicer must establish or make good-faith efforts to establish live contact with a delinquent borrower.
- By day 45 of delinquency: The servicer must provide written notice describing required information and, when applicable, loss-mitigation options.
- Within 5 days: Under 12 CFR 1024.41, the servicer generally must acknowledge a loss-mitigation application in writing within 5 days, excluding legal public holidays, Saturdays and Sundays.
- Before the first foreclosure notice or filing: 12 CFR 1024.41(f)(1) generally prohibits the first notice or filing for a judicial or non-judicial foreclosure process until the mortgage loan obligation is more than 120 days delinquent, subject to the regulation’s stated exceptions. This provision was amended most recently at 90 FR 20792.
Regulation X does not universally require Certified Mail for every early-intervention or loss-mitigation letter. It establishes notice, content and timing requirements. Your institution may choose Certified Mail to create a stronger evidence trail showing when a letter entered the USPS mailstream, where it went and whether delivery was attempted or completed.
For FHA loans, 24 CFR 203.606 requires the mortgagee, before initiating foreclosure, to notify the mortgagor in a format prescribed by the Secretary that the borrower is in default and that the mortgagee intends to foreclose unless the default is cured.
The FHA rules also changed. The 2024 HUD modernization rule, 89 FR 63098, rewrote 24 CFR 203.604. The former general 36-day default-letter and 17-day referral timing is no longer the current rule. Today, the verifiable certified-letter minimum in §203.604(b)(3) applies specifically to mortgages insured on Indian Land under section 248 of the National Housing Act. That reasonable-effort process includes at least one letter certified by the Postal Service as dispatched, at least one trip to the property and a documented telephone call.
Flood-related mailings also require careful execution. 42 U.S.C. §4012a(b) generally bars regulated lenders from making, increasing, extending or renewing loans secured by improved real estate in a special flood hazard area without required flood insurance. 42 U.S.C. §4104a requires written flood-hazard notice to the borrower and servicer a reasonable period before the applicable transaction.
What Proof Do Servicers Need In An Audit-Ready File?
Here is just a few of the records your servicing, compliance and loss-mitigation teams may need to retrieve quickly:
- Proof of mailing with the postmark date matched to the delinquency timeline.
- USPS acceptance scan tied to the Intelligent Mail Postal Barcode.
- Certified Mail tracking events showing delivery or attempted delivery.
- Available Electronic Return Receipt signature records.
- A notarized affidavit of mailing.
- The PDF letter or notice associated with the mailing.
- The address list or borrower record used for the mailing.
- Every notice searchable for 10 years across the servicing life of the loan.

A complete archive helps you respond to CFPB supervision inquiries, internal audits, borrower disputes, foreclosure counsel requests and investor or agency reviews without searching through paper files or disconnected spreadsheets.
How Much Can Notice And Documentation Problems Cost?
The cost of getting it wrong is not limited to postage. RESPA Section 6(f), referenced in 12 CFR 1024.41(a), permits private actions for certain violations, including actual damages and statutory damages in applicable circumstances. Institutions may also face CFPB supervision findings, restitution plans, foreclosure rescissions and repurchase demands tied to documentation defects.
A stronger mailing process can also reduce certified mail cost:
- Paper green-card Return Receipt: $4.65 per piece.
- Electronic Return Receipt: $2.91 per piece.
- Savings: $1.74 per piece.
- Across 5,000 delinquency notices: $8,700 saved.
- Across 25,000 notices: $43,500 saved.
A full 1-ounce Certified Mail letter with Electronic Delivery Confirmation is shown in the comparison used for this page at $7.28 online versus $11.02 at the counter, a difference of $3.74 per piece. Rates and service fees can change, so confirm the applicable amount in USPS Notice 123 when building your current mailing budget.
How Certified Mail Labels Fits Your Servicing Workflow
You can choose the workflow that fits your volume, staffing and technology.
Self-Print Labels For Exceptions And Individual Notices
For a low-volume exception, create and print a USPS Certified Mail label online through our label-printing flow.
- No trip to the Post Office.
- No PS Form 3800 preparation.
- No postage meter.
- No equipment lease.
- Print on a standard office printer or adhesive sheets.
- Receive live USPS postage and a trackable barcode.
- Keep the mailing record with the borrower file.
Print & Mail For Loss-Mitigation And Default Campaigns
Upload your PDF letter and address list, and we handle the physical mailing through our Print & Mail service.
- We print the letter.
- We fold and insert the document.
- We apply postage and Certified Mail.
- We present the mailing to USPS.
- Orders received before 5:00 PM Eastern are mailed the same business day.
- A 1-page letter is available at $8.43 in the workflow described for this service.
- You receive USPS proof of acceptance.
- You receive a notarized affidavit of mailing.
- You can review tracking and delivery records without handling envelopes in-house.
Bulk Certified Mail For Monthly Delinquency Letters
Use Excel or CSV uploads for monthly delinquency letters, flood notices, escrow correspondence, payoff letters and other recurring campaigns. The bulk mailing workflow lets your team prepare large groups of labels without entering every address manually.
For higher volume, connect your servicing platform through API or secure SFTP automation. Your batch can be processed with a single USPS SCAN form so the mailing is accepted in one organized scan.
You’ll get:
- Bulk Certified Mail processing.
- Fewer manual address-entry errors.
- Tracking data tied to each piece.
- Electronic Return Receipt options.
- Reports for operations and compliance teams.
- A repeatable process for banks, credit unions, subservicers and mortgage service providers.
Electronic Return Receipt USPS Options
When your policy or counsel calls for signature evidence, add Electronic Return Receipt. It provides a digital record instead of the traditional green card, helping your team search, download and attach delivery evidence to the appropriate loan or case file.
Build A More Defensible Mailing Process Today
Certified Mail Labels has created more than 33 million labels and served more than 200,000 customers since 2006. We are BBB Accredited and trusted by Fortune 500 companies.
You get a modern mailing process without monthly fees, contracts or equipment leases. You get same-business-day Print & Mail, bulk certified mail automation, certified mail tracking, Electronic Return Receipt options and a free 10-year searchable compliance archive.
Create and print USPS Certified Mail labels online, upload your next campaign for Print & Mail, or review your Certified Mail reports today. Save time, reduce administrative work and keep the proof your institution needs in one searchable place.
Last reviewed October 1, 2026. Rates verified against USPS Notice 123; Regulation X, HUD and NFIP citations verified against the eCFR and U.S. Code. Federal and state mortgage-servicing rules shift. Re-verify citations quarterly and confirm specifics with counsel.
Frequently Asked Questions
What Does Regulation X Require By Day 36 And Day 45 Of Delinquency?
By day 36, 12 CFR 1024.39 requires live contact or a good-faith effort to establish live contact. By day 45, the servicer generally must provide written notice with the required information and applicable loss-mitigation information.
When Can The First Foreclosure Notice Or Filing Be Made?
Under 12 CFR 1024.41(f)(1), the first notice or filing generally cannot be made until the borrower’s mortgage loan obligation is more than 120 days delinquent, subject to stated exceptions and other applicable requirements.
Does HUD Still Require A Certified Letter Before FHA Foreclosure?
Not as a general certified-letter requirement for every FHA loan. After the 2024 modernization rule, the specific certified-letter minimum in 24 CFR 203.604(b)(3) applies to mortgages insured on Indian Land under section 248. 24 CFR 203.606 separately requires the FHA pre-foreclosure review notice.
What Flood Notices Must Servicers Send?
Flood notices generally warn the borrower and servicer when improved real estate securing a loan is in a special flood hazard area and explain applicable flood insurance purchase requirements. 42 U.S.C. §4012a(b) and 42 U.S.C. §4104a provide the federal anchors. The timing and exact notice workflow should be confirmed for the transaction and jurisdiction.
How Do We Prove Thousands Of Delinquency Letters Were Mailed?
Upload an address list through Excel/CSV, API or SFTP, or use Print & Mail for a full-service campaign. You can receive USPS acceptance scans, SCAN form records, postmark dates, Intelligent Mail Postal Barcode data, tracking events, available signature records and a notarized affidavit of mailing. Records remain searchable in the 10-year archive.
What Does Electronic Return Receipt Cost Compared With The Green Card?
Using the comparison figures for this page, paper Return Receipt is $4.65 and Electronic Return Receipt is $2.91, saving $1.74 per piece. Check current USPS Notice 123 pricing before launching a new campaign.
Certified Mail Labels provides the mailing and the proof, not legal advice. Confirm notice requirements with your own counsel.